
Key Takeaways
- A lower monthly payment does not always mean lower borrowing costs.
- Compare APR, fees, repayment length, and the total amount you will repay.
- Personal loans can provide predictable payments, while credit cards offer flexible access to credit.
- Home equity borrowing may offer favorable terms, but it places your home at risk if you cannot repay.
- Detroit borrowers should review multiple written offers before committing to financing.
- For nonurgent purchases, saving may be a better choice than borrowing.
Whether you are handling furnace repairs during a Michigan winter, updating an older Detroit home, consolidating debt, or covering an unexpected household expense, the way you borrow matters. Working with a credit union in Detroit or another local financial institution can allow you to discuss options, payment expectations, and loan terms in person. The best choice is rarely the option with the smallest payment displayed first. A careful comparison should account for the full cost, the repayment timeline, the impact on your budget, and the risk associated with the type of credit you choose.
Why Comparison Matters
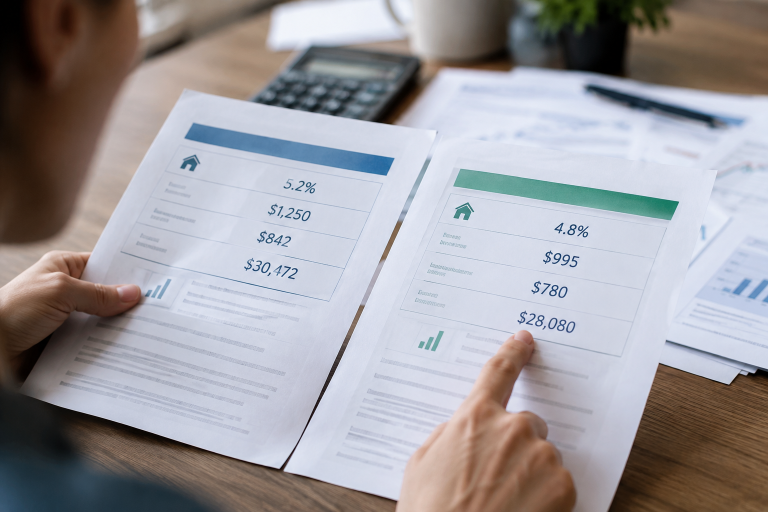
A longer repayment term can reduce the monthly bill, but it can also increase the total interest paid over time. For example, the payment on a $10,000 balance spread across seven years may look easier to manage than a three-year loan, yet the longer term generally keeps the debt outstanding longer and can add to total borrowing costs.
When comparing offers, look beyond the payment and consider:
- The interest rate and APR
- Origination, annual, late, and closing fees
- The number and size of payments
- Whether the rate is fixed or variable
- The total amount repaid by the final due date
How Personal Loans Work
A personal loan usually provides a lump sum that is repaid in regular installments over a set period. Many are unsecured, meaning you do not pledge an asset as collateral, although secured personal loans also exist. Detroit residents may use personal loans for vehicle repairs, moving costs, medical expenses, home repairs, or consolidating higher-cost balances.
Potential Benefits
- Set payments can make monthly planning easier.
- A fixed payoff date gives the borrower a clear endpoint.
- A lower-cost loan may help when replacing more expensive debt, provided spending does not create new balances.
Points to Watch
Review origination fees, late-payment consequences, prepayment terms, and the full repayment amount. Borrowing more than a household budget can comfortably support can turn a useful financing tool into a long-term strain.
When Home Equity May Fit
Homeowners may consider a home equity loan or home equity line of credit, often called a HELOC. A home equity loan generally provides a lump sum, while a HELOC allows qualifying borrowers to draw from an approved credit line during a defined draw period. Because the home serves as collateral, home equity products may have different pricing and qualification standards than unsecured borrowing. That potential advantage comes with significant risk. Serious default can put the home at risk, and a variable-rate line of credit may have payments that change over time.
- May fit: A substantial, planned expense such as a major repair or renovation.
- May not fit: Short-lived purchases or expenses that can reasonably be saved for.
- Ask about: Closing costs, appraisal requirements, draw periods, repayment periods, and rate adjustments.
Homebuyers and owners exploring mortgage-related options can review government-backed home loans and mortgage assistance programs to understand broad eligibility paths and available assistance information.
Where Credit Cards Make Sense
Credit cards are revolving credit, meaning available credit can be used again as the balance is repaid. They can work well for routine purchases, short-term expenses, and situations where the balance will be paid in full by the due date. They may become costly when balances remain for many billing cycles. Before using a card for a large expense, ask whether the balance can be cleared quickly. Also review the regular purchase APR, the length and conditions of any promotional offer, balance transfer fees, and what happens after a late payment.
How to Calculate the True Cost
Interest rate and APR are related but not identical. The APR includes the interest rate plus certain lender charges, which can make it more useful for comparing similarly structured loan offers.
For a simple estimate, add all scheduled payments and applicable upfront fees, then subtract the amount borrowed. The result is the estimated cost of borrowing. Compare that figure across personal loans, home equity products, and credit card repayment plans.
How Credit and Income Affect Offers
Lenders commonly consider credit history, income, existing monthly debt, requested amount, and repayment term. The debt-to-income ratio compares monthly debt obligations to gross monthly income. A higher ratio can limit borrowing choices or affect the terms offered. Before applying, check your credit reports for errors, pay bills on time, reduce balances where possible, and avoid opening several new accounts at once. These steps do not guarantee approval, but they can help you approach borrowing with a clearer financial picture.
A Simple Comparison Process
- Define the purpose. Decide whether the expense is urgent, necessary, or optional.
- Set a budget-based limit. Do not borrow simply because a lender offers a larger amount.
- Get multiple offers. Compare at least three written options when practical.
- Compare like with like. Review APR against APR, and account for fees and term length.
- Read the agreement. Confirm payment dates, rate changes, collateral, and late-payment terms before signing.
Common Mistakes to Avoid
- Choosing based only on the lowest monthly payment.
- Ignoring fees or a promotional rate expiration date.
- Using home equity for purchases with little lasting value.
- Transferring card debt without a realistic payoff plan.
- Accepting the first offer without comparison shopping.
- Leaving no room in the budget for savings or unexpected expenses.
Final Decision Checklist
- Is the expense necessary or time-sensitive?
- Can the payment fit after essential household costs and savings?
- What is the APR, and what fees apply?
- How much will be repaid in total?
- Is the rate fixed or variable?
- Is collateral involved?
- Can the balance be paid off early without a penalty?
Conclusion
For Detroit borrowers, the right financing choice depends on the cost, the expected repayment timeline, and the level of financial risk that aligns with the household’s goals. Personal loans can provide predictable monthly payments for eligible borrowers who need a set amount of money for expenses such as debt consolidation or unexpected bills. Home equity loans and lines of credit may help finance larger planned projects, but they use the home as collateral and can put the property at risk if payments are not made as agreed. Credit cards may be convenient for smaller purchases or expenses that can be repaid quickly, particularly when the card’s terms suit the borrower’s needs. However, carrying a balance can become costly when interest charges accumulate. Before choosing any financing option, compare the annual percentage rate (APR), fees, repayment period, monthly payment, and consequences of missed payments. Consider how the new obligation will fit alongside existing bills and savings goals, and avoid borrowing more than necessary. Comparing the complete terms, not just the advertised payment, can help Detroit households make informed decisions and choose financing that aligns with their budget and long-term financial priorities.
Veeramachineni Lalitha

I am Finance Content Writer. I write Personal Finance, banking, investment, and insurance related content for top clients including Kotak Mahindra Bank, Edelweiss, ICICI BANK and IDFC FIRST Bank. My experience details : Linkedin