
Buying a home used to mean proving the same thing in the same way, no matter who you were. Lenders looked for a narrow set of signals (such as steady income, long credit history, and predictable financial behavior). So, if you didn’t fit that mold, you were less likely to get approved, even if you managed your money responsibly.
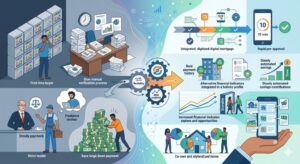
Fortunately, that structure is now being reshaped by a broader set of players across housing, finance, and technology. Professionals working at the intersection of these areas, such as those highlighted in this Crunchbase profile, are part of a shift toward more flexible and integrated approaches to how homes are built, financed, and brought to market.
Credit scores sit at the center of that system. They compress years of financial activity into a single number that can determine whether someone qualifies for a loan and at what cost. For first-time buyers, especially those early in their careers, that score often reflects a short or incomplete history rather than actual financial discipline.
The process itself makes it all the more challenging. Applications require layers of documentation that must be reviewed and verified, often more than once. That slows everything down and creates multiple points where delays can creep in. For buyers competing in active markets, even small delays can matter.
Repeat buyers typically move through this system with fewer obstacles because they’ve already established the signals lenders expect. First-time buyers, by contrast, are asked to meet those expectations without the same history. The result is a process that filters people out before fully considering how they actually manage their finances.
Why Your Financial Story Matters More Than Your Credit Score
That narrow view of credit is starting to change. Instead of relying almost entirely on a score, newer approaches look at patterns that reflect day-to-day financial behavior. Rent payments, utility bills, and recurring expenses all provide evidence of consistency that older models tend to ignore.
For someone without a long credit history, this makes a real difference. A track record of paying rent on time can now carry weight in ways it didn’t before.
According to TransUnion, when rent payments are added to credit files, about 9% of previously unscorable consumers become scorable, often landing in a range where lenders can begin evaluating them more seriously.
This matters even more for buyers whose income doesn’t follow a traditional structure. Freelancers and contract workers often earn money in uneven intervals, which can look risky under rigid underwriting models. A broader evaluation can account for that variability and still recognize stability over time.
There’s a tradeoff here. Expanding the data used in lending introduces new questions about fairness and accuracy. Automated systems rely on the data they are trained on, and if that data is flawed, the results can be too. Access improves, but it has to be paired with oversight to ensure decisions remain consistent and fair.
The 10-Minute Pre-Approval Is Replacing the 3-Week Wait
Speed has changed the early stages of buying a home. What used to take weeks of back-and-forth can now happen in a much shorter window. Applications move online, documents are uploaded instantly, and initial decisions arrive far faster than before.
That change carries weight in competitive situations. Sellers tend to favor buyers who appear ready to move forward without delays. Buyers aren’t just moving faster because they have to—they expect to. Research from MeridianLink shows that about 90% of homebuyers are interested in a fully or mostly digital mortgage process, largely due to the speed and simplicity it offers.
Behind that faster experience is a high degree of automation. Systems can verify income and financial data without the same level of manual review, which reduces processing time and keeps applications moving. It also allows lenders to handle a higher volume of requests without creating bottlenecks.
Still, speed at the front doesn’t eliminate the rest of the process. Additional documentation can still be required, and approvals can still hinge on detailed financial checks. But improvements in the process mean that it no longer stops buyers at the starting line.
Saving for a Home No Longer Starts With a Lump Sum
Saving for a down payment has long been one of the biggest obstacles for first-time buyers. The expectation has been simple: build a large amount of cash before even considering a purchase. For many, that timeline stretches out for years. Data cited by National Mortgage Professional shows that the typical U.S. household now needs about seven years to save for a down payment, which helps explain why so many buyers struggle to enter the market under traditional expectations.
A different approach is starting to take hold. Instead of relying on a single lump sum, savings can build gradually through automated contributions tied to income or spending. Small amounts set aside consistently begin to accumulate without requiring constant attention.
Some systems go a step further by allowing those funds to grow while they’re being saved. Rather than sitting idle, money can be placed into options that aim to increase its value over time. That changes how buyers think about preparation. It becomes less about hitting a fixed number and more about steady progress.
There are also paths that reduce the need for a traditional down payment altogether. Shared ownership and co-buying structures distribute costs across multiple participants, making it possible to enter the market earlier. These models don’t remove financial responsibility, but they do change how that responsibility is structured.
Financing Is Getting More Flexible—But Also More Complicated
More options are now available when it comes to structuring a home purchase. Buyers can approach financing in ways that better match their financial situation, rather than fitting into a single standard format. That flexibility can open doors for people who might not qualify under stricter terms.
Some of these options change how upfront costs are handled. Instead of paying everything at once, certain expenses can be spread out or incorporated into the overall financing plan. That lowers the immediate barrier to entry and allows buyers to move forward sooner.
But having more options also means more decisions. Each structure comes with tradeoffs that affect long-term affordability. A setup that feels manageable in the short term may carry higher costs over time, depending on how payments are arranged. Access alone doesn’t guarantee a better outcome. When it becomes easier to enter the market, it also becomes easier to take on commitments that stretch beyond what a buyer can comfortably sustain. Understanding the details behind each option matters just as much as qualifying for it.
The Home Search and the Loan Are Becoming One Experience
The process of finding a home and securing financing used to happen in separate steps. Buyers would identify a property first, then begin the process of securing a loan, often moving between multiple providers to complete each part.
That separation is starting to fade. Buyers can now explore homes while simultaneously seeing how different financing options apply to each one. Instead of estimating affordability in general terms, they can evaluate specific properties against their financial position in real time.
Keeping everything in one place reduces friction. Communication becomes simpler, timelines shorten, and fewer steps fall through the cracks. For first-time buyers, this can make the process feel more manageable and less fragmented. At the same time, the pace of decision-making increases. When browsing and financing are closely connected, the gap between interest and action becomes smaller. That can help in competitive situations, but it also requires buyers to stay deliberate rather than reactive.
Where Fintech Still Falls Short
Even with these changes, some challenges remain. Regulations continue to shape how financial products are offered and approved, and those requirements can slow down the adoption of new methods. They exist for a reason, but they also limit how quickly systems can adapt.
Data privacy is another concern that hasn’t been fully resolved. Expanding the types of financial information used in lending means more personal data is being collected and analyzed. Buyers need confidence that this information is handled responsibly and protected from misuse.
Automated decision-making introduces its own risks. When algorithms are responsible for evaluating applications, the way they are designed becomes critical. If the underlying data reflects existing biases, those patterns can carry through into new systems.
Access has improved, but it hasn’t expanded evenly. Some buyers benefit more than others depending on their financial situation and access to technology. The system is changing, but it hasn’t removed every barrier.
What This Means for First-Time Buyers
The group of people who can realistically buy a home is starting to widen. Buyers who may have been overlooked under older systems now have additional ways to qualify. That includes those with limited credit history or income that doesn’t fit traditional patterns.
Lenders are responding by adjusting how they evaluate applicants. Competition is pushing them to consider a broader range of financial behaviors, which leads to more tailored options for different types of buyers. The process is no longer defined by a single path.
The idea of a qualified buyer is becoming less rigid. Instead of relying on a narrow checklist, lenders are looking at a wider set of signals to assess readiness. That doesn’t remove risk, but it changes how that risk is understood.
More access brings more responsibility. Buyers have more choices than before, but those choices require careful evaluation. Entering the market may be easier, yet long-term stability still depends on making decisions that align with a buyer’s financial reality.
Veeramachineni Lalitha

I am Finance Content Writer. I write Personal Finance, banking, investment, and insurance related content for top clients including Kotak Mahindra Bank, Edelweiss, ICICI BANK and IDFC FIRST Bank. My experience details : Linkedin